Last mile logistics 2021-2: New state of the industry report
As the global pandemic recedes, this report analyses the last mile challenges and opportunities facing retailers and 3PLs and major industry trends going into next year.
Last mile logistics is booming. You only need to take a cursory look at the amount of capital being invested in this industry to understand that. It’s a fertile time for providers in this space. And the huge influx in home deliveries resulting from the pandemic has seen demand skyrocket for innovative solutions that help retailers and logistics companies manage one of their largest supply chain costs.
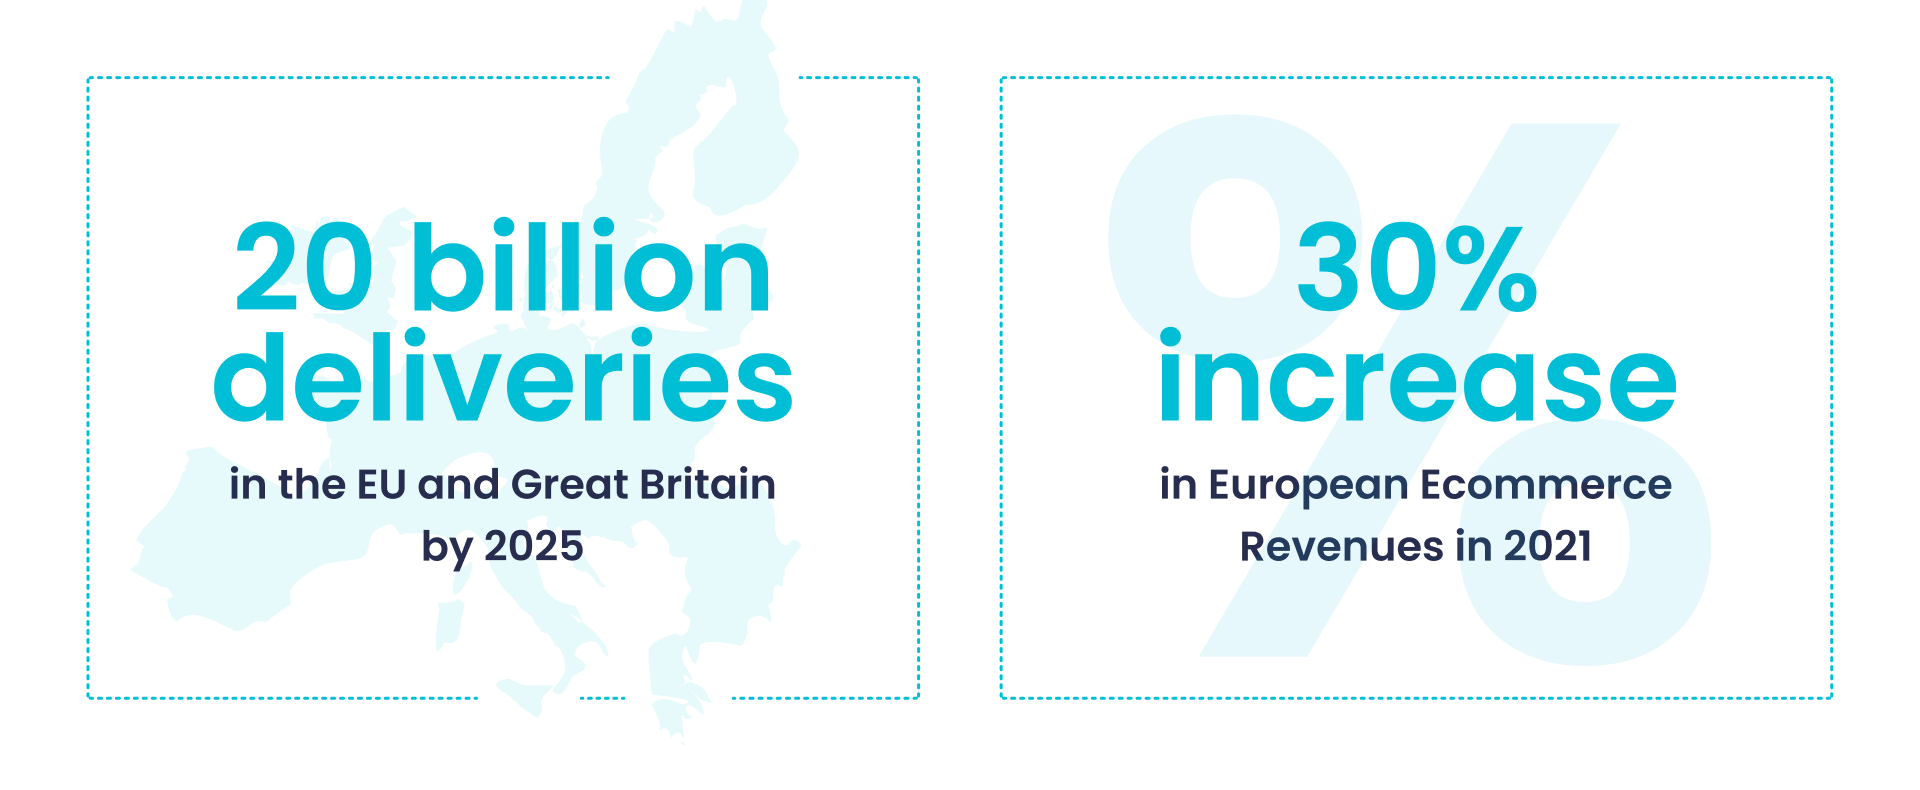
Forecasts indicate that the EU and Great Britain could see as many as 20 billion B2C deliveries a year as soon as 2025. In 2021 alone, a 30% increase is expected in ecommerce revenues across Europe.
As tantalising as the potential rewards may be, the fact remains that margins on deliveries remain incredibly squeezed. After all, the last mile may be the shortest leg of the delivery journey, but it accounts for more than 50% of total shipping costs. And it accounts for a similarly large proportion of total emissions per package.
This report analyses new and recent trends in the last mile industry. We assess some of the methods that agile retailers and logistics companies are using to cut their costs and emissions. And the continuing role of third party logistics in supply chain management. The global pandemic may be receding, but its effects are still being felt in logistics.
As shippers scale up ever-more complex delivery networks to meet this burgeoning demand for deliveries and heightened consumer expectations for instant gratification, it becomes increasingly difficult to maintain clarity across their last mile logistics.
The added pressure to lower emissions only increases the need for new solutions to these challenges, driven by innovations in automation and a reframing of perspectives among senior leaders from delivery operations to delivery experiences.
We will consider:
-
The Aftermath of the Pandemic on Last Mile Logsitics
-
More Complicated Delivery Networks
-
Greater Degrees of Automation
-
The Continuing Rise of Experiential Deliveries
-
Emissions Continue Upwards Trajectory
The Aftermath of the Pandemic on Last Mile Logistics
Enough has already been said about the impact of the global pandemic on the supply chain and last mile logistics in particular. Suffice to say that 2020 saw the volume of B2C parcels delivered across the EU and Great Britain exceeded 10 billion for the first time. This is a figure that Last Mile Experts expects to reach 20 billion in less than five years and 40 billion by 2029. That’s an acceleration of four-six years compared to pre-COVID 19 projections.
Deloitte notes that last mile growth was already very strong prior to the pandemic. This is a result of the shift in consumer appetites to online buying modes. As a result, businesses were already facing mounting pressure that was driving steady innovation.
Then came the pandemic. The steady expansion gave way to a sudden, chaotic explosion in demand.
This gave a huge advantage to businesses that already had delivery systems in place. They could rapidly add capacity and offer new services or capabilities. Those without existing infrastructure were forced to rely instead on 3PLs and gig economy services to reach their customers.
What Comes Next?
With the economy reopened, a lot of the chaos has now receded. But there things are unlikely to go back to how they were pre-pandemic. The focus on safety remains a major consideration moving forward, with contactless delivery workflows establishing a new normal for door-to-door interactions.
Even once the pandemic has receded, some experts warn that retailers and logistics companies must be ready to deal with further distortions to the supply chain. Still in late 2021, we are seeing consumers hoard products that they rationally know won’t run out. Most acutely, we witnessed this with the UK petrol shortage in September. It only took a slight drop in supply as a result of the driver shortage disrupting fuel deliveries to cause a spike of panic buying that left pumps dry and forecorts closed.
According to behaviour experts, this response is a psychological mechanism to make consumers feel more in control over their fate in the face of the pandemic. But hoarding doesn’t necessarily result in greater consumption, so shippers that see these spikes must be prepared for a subsequent drop in demand.
Following the toilet paper shortage at the beginning of lockdown, Robert Boute, Professor of Supply Chain Management at Vlerick Business School and KU Leuven explained:
The distortion of the demand pattern aggravates as we move more upstream in the supply chain to the end suppliers. They will face a highly unpredictable demand in the months to come.
Robert Boute, Professor of Supply Chain Management at Vlerick Business School and KU Leuven
ConclusionGrowth in home deliveries is on an accelerated path due to COVID-19. Even as the immediate effects of the pandemic recede, B2C deliveries are expected to double in Europe over the next five years. But shippers will need to pay close attention to the continued prevalence of distortions in the supply chain as a result of changes in consumer psychology brought on by the pandemic. Failure to account for this ‘Bullwhip Effect’ can have severe long-term consequences. |
More Complicated Delivery Networks
As demand for rapid and low-cost deliveries continues to rise, last mile logistics becomes much more complicated for shippers. Two-day delivery is now a minimum expectation for many verticals outside of big and bulky. But it requires goods to be stored closer to recipients. The upshot of this is that micro fulfilment has become a necessity for more shippers. A retailer that might previously have had one or two distribution centers now requires at least five. For next-day delivery, the optimal number of locations increases exponentially to as many as 40.
Rising Demand for 3PLs
Such huge infrastructure costs are an unrealistic expense for most. Some have found creative ways to increase their warehousing space, through the use of ‘dark stores’ (repurposing of closed stores as local fulfilment centers) during the pandemic – a trend that shows signs of continuing as stores reopen, with supermarkets doubling up as local fulfilment centers.
But the ever-present need to deliver higher volumes, faster means that the role of third party logistics in supply chain management continues to grow. As a result of this drive for multi-carrier delivery operations, the global 3PL market is on course to exceed $1.3 trillion by 2024. In the US, 90% of Fortune 500 companies work with at least one 3PL. That’s almost double the level seen two decades ago.
But constraints such as cost, coverage and areas of specialisation mean it’s not just the volume of 3PL deliveries that’s rising. It’s also the number of carriers each shipper needs to work with to scale their delivery operations. The effect of these knottier delivery networks is a relative lack of visibility for shippers across the totality of their last mile operations, which are becoming much more fragmented across internal fleets and multiple external carriers.
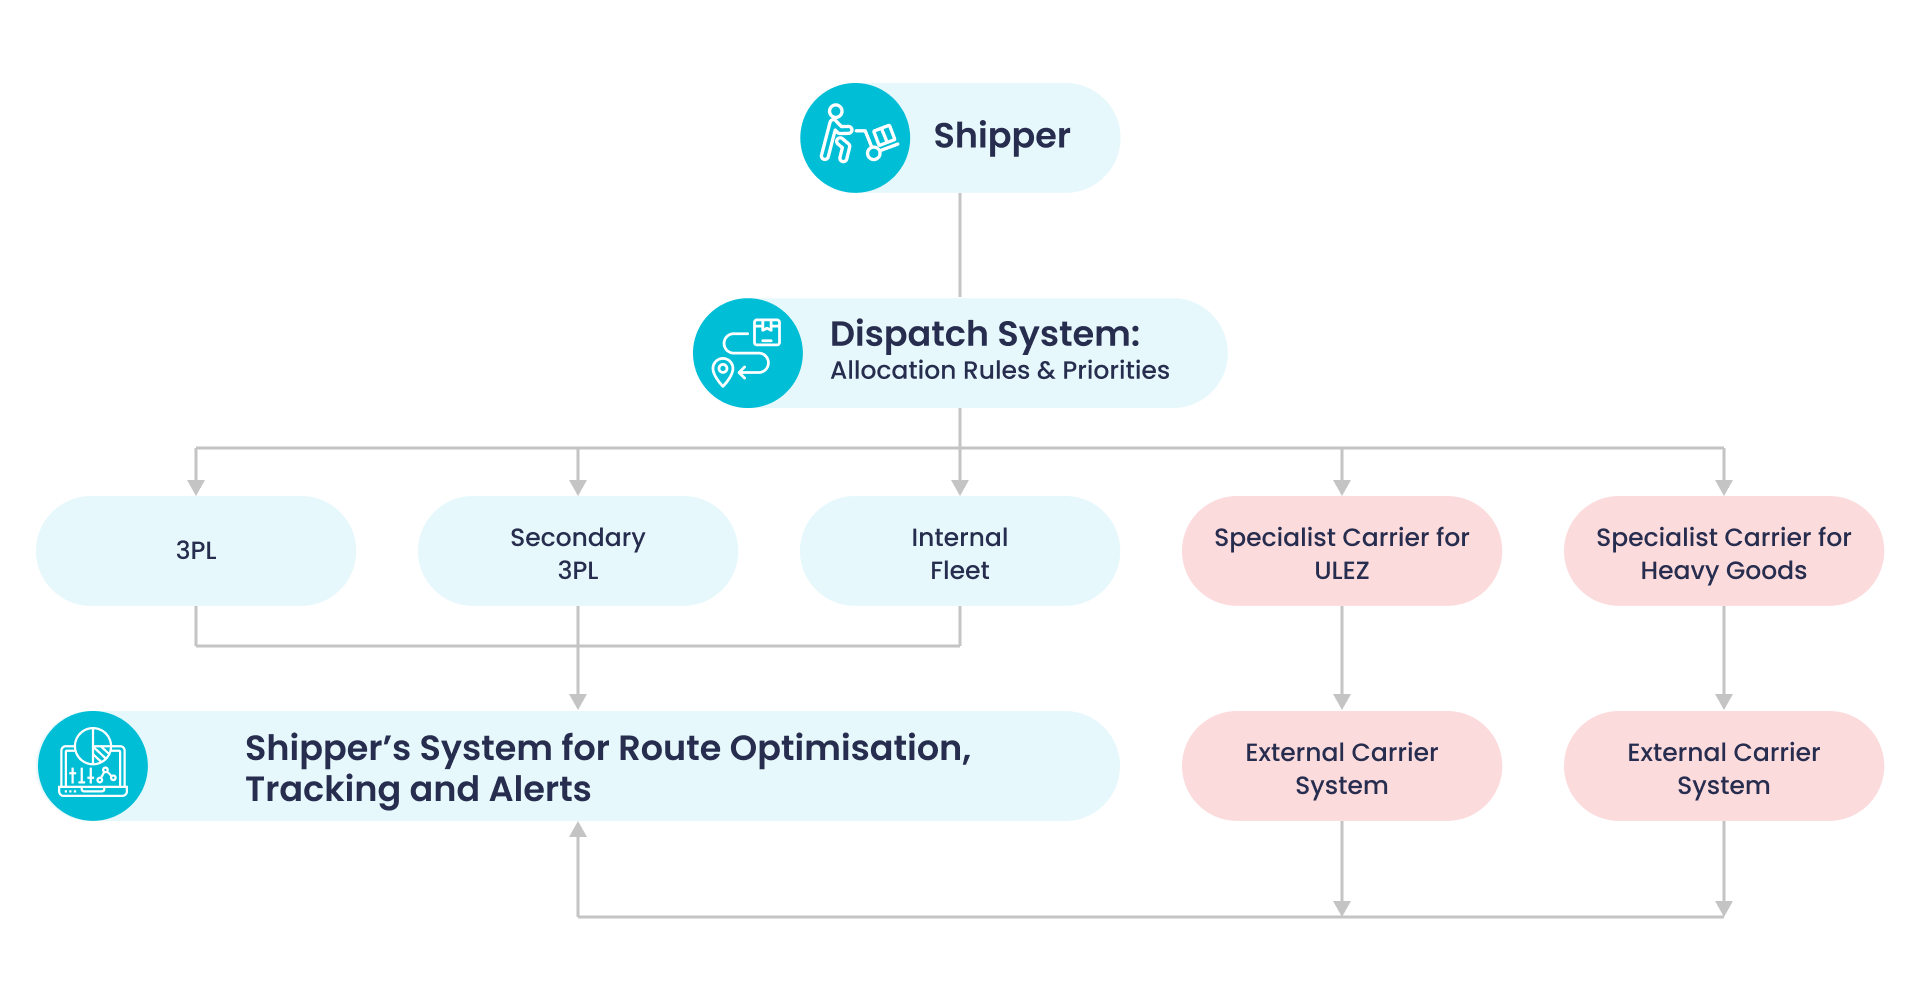
ConclusionThe need to scale deliveries and increased consumer demand for shorter delivery times have conspired to create a situation whereby shippers need more local fulfilment capacity. Outside of creative solutions such as dark stores, the prohibitive infrastructure costs and time to scale capacity mean most shippers are turning to 3PLs to build up their networks more quickly. As a result, many retailers are struggling to maintain real-time visibility over their last-mile operations. |
Greater Degrees of Automation
The need to manage operational costs against a backdrop of greater logistical complexity is driving more retail and logistics companies to invest in automation. In the last mile, automation can disrupt every part of the supply chain, including:
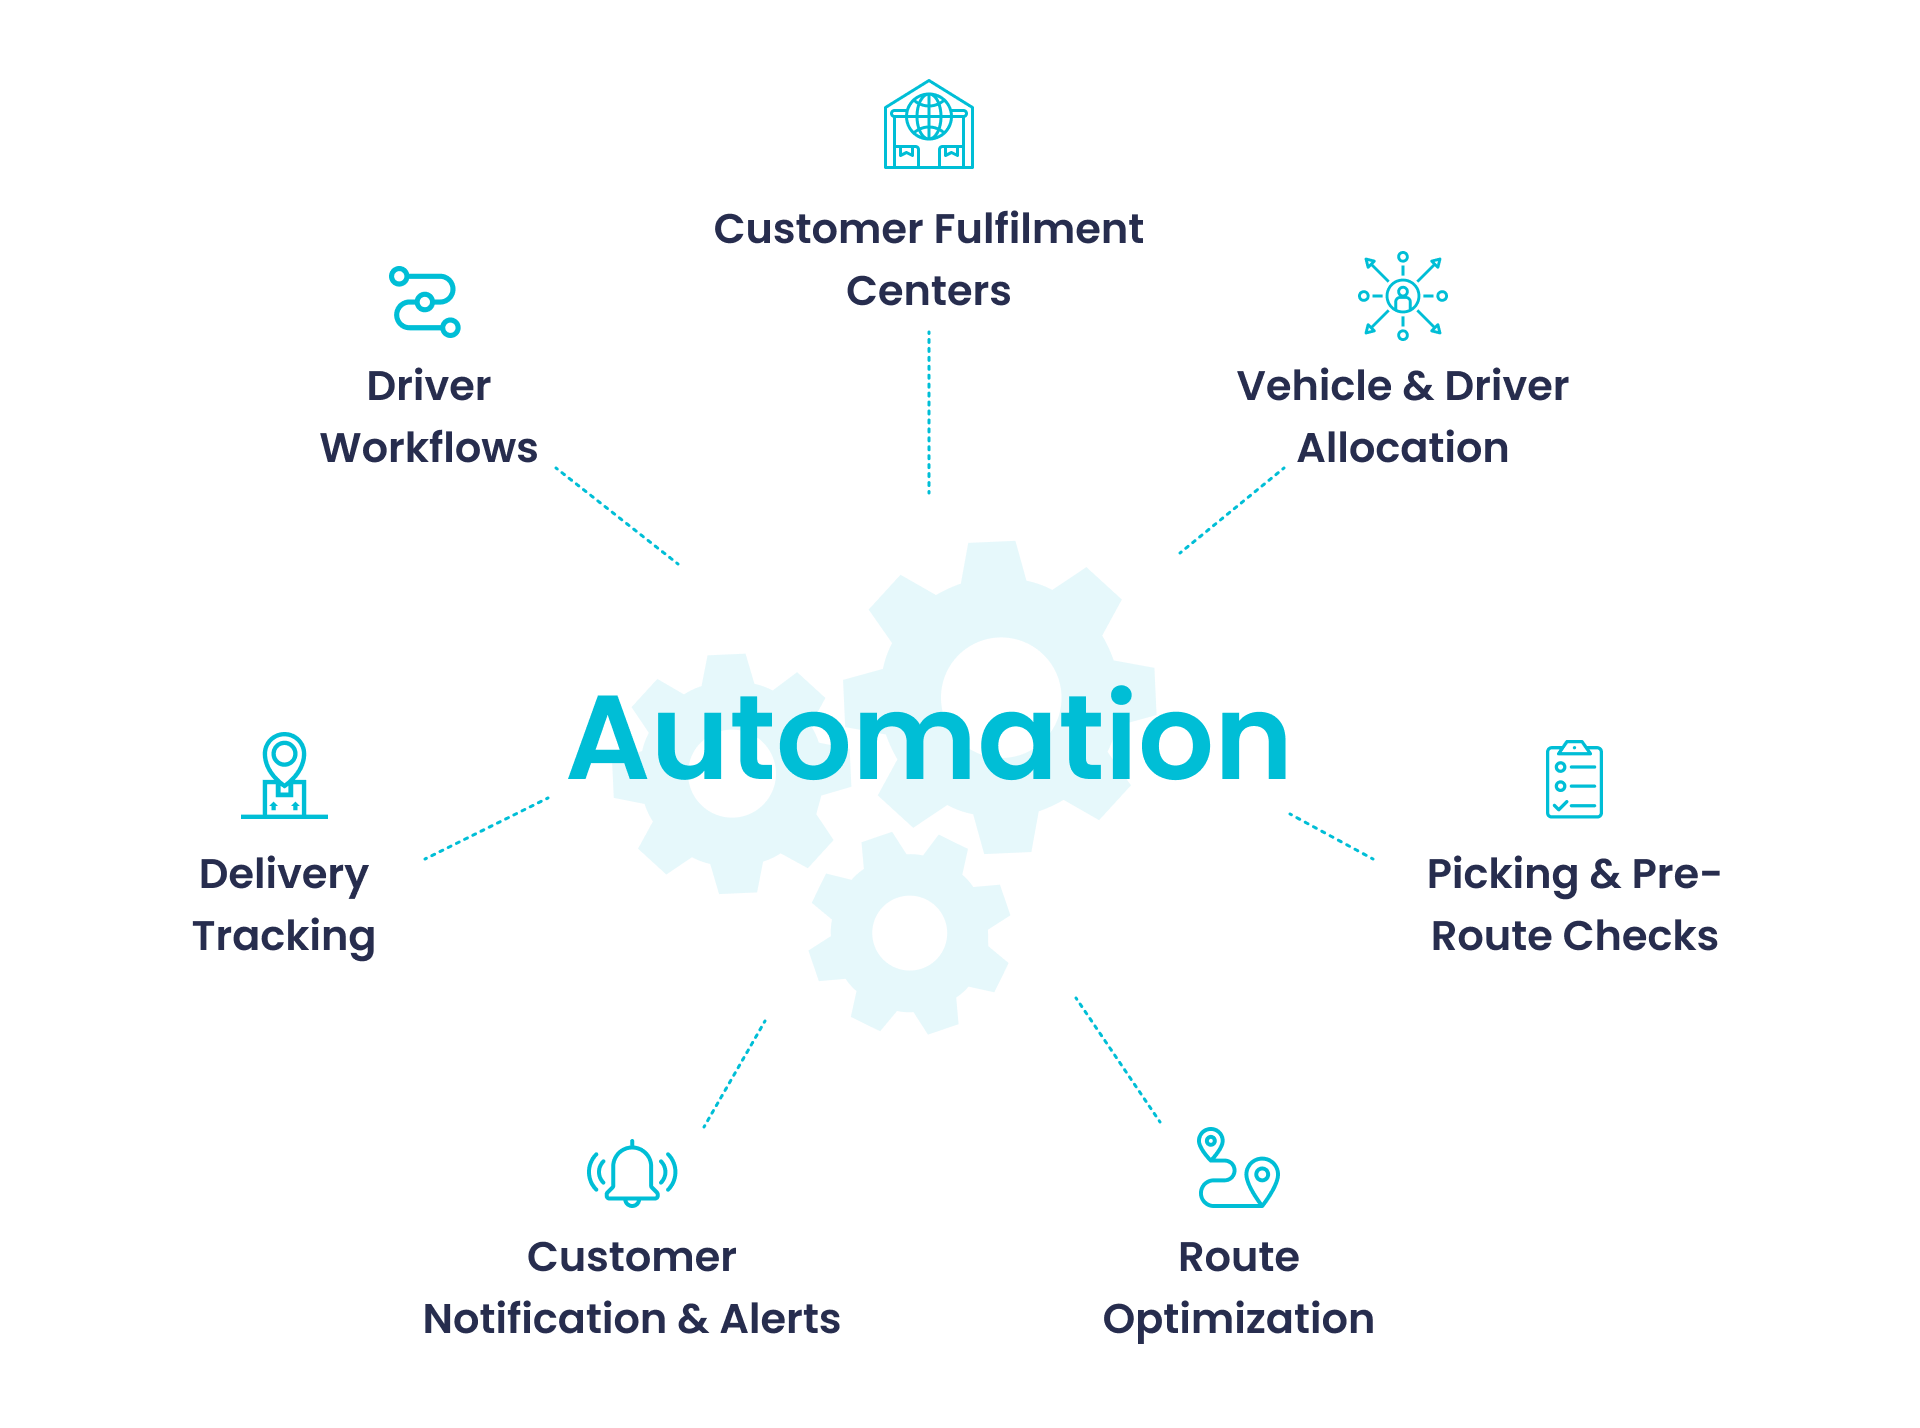
Typically, last mile delivery management platforms will support all of these processes with automations apart from the planning and movement of goods in the customer fulfilment center. These platforms tend to comprise a desktop environment for dispatchers, a smartphone application for drivers and a web experience for customers.
Customer Fulfilment Centers
Automation can optimise product location to speed up order handling and subsequently cut costs. Advanced fulfilment centers can also make use of robotics to move palettes, with human pickers stepping in at the end of the process.
Vehicle and Driver Allocation
Using algorithms to allocate deliveries across carriers, fleets and drivers is a great way to ensure your operation runs efficiently with the highest possible drop density. The algorithm can account for hundreds of variables and optimise based on your requirements, for instance, preferring a greener carrier or ensuring that frozen food is only loaded into refrigerated vehicles.
Some advanced algorithms have the potential to go even more granular, enabling you to account for variables such as constraints based on vehicle type (e.g. a two-wheeled vehicle can cut through a park, while an electric vehicle can enter a ULEZ at no extra cost), service time, walking distance from the premise and more.
They can also account for the changing free capacity of vans as delivery rounds are completed, then combine drop offs and pickups to further increase efficiency.
Picking and Pre-Route Checks
Last Mile delivery management platforms can help speed many processes around picking, making it easy for drivers to quickly scan barcodes as they load vans and take them through vehicle-checks and other pre-route processes.
Route Optimisation
Once drivers have been assigned and vehicles filled, algorithms can optimise the routes and order in which deliveries are fulfilled to minimise driving and wait times. With commercial-grade mapping, the type of vehicle being routed can be considered. So drivers won’t get stuck in roads where they don’t have space to turn around or pass through congestion zones and ULEZs that might levy a charge on their vehicles.
This process is usually completed together with the allocation, as the algorithm will consider all of these routing factors when deciding which packages to put in which vans.
Driver Workflows
Now that every driver has a smartphone, it is possible to automate many of the workflows they need to complete a delivery. Doorstep processes involving returns, empties, damaged goods, payments, contactless proof of delivery, identify verification and age checks can all be simplified with the use of the right app.
Delivery Tracking
Because the drivers app is tied into the last mile delivery management system, dispatchers maintain a real-time view of the movement of every parcel in the field. Everything can be uploaded, analysed and reported on, from delays and deviences from the planned routes, to issues encountered in the field and reported back through the app.
Customer Notifications and Alerts
One of the most effective automations for the overall customer experience is the ability for these systems to push updates to recipients in real time about the status of their orders. If a delay is expected, or if they are next in the queue, personalised messages can be sent out via email or SMS, and changes will also be reflected on the customer track and trace page.
ConclusionRetailers and 3PLs are increasingly turning to automated solutions to help them ensure a greater degree of efficiency and cost-effectiveness in the last mile. Automation has the potential to transform the entire process, from warehouse management to vehicle allocation, route optimisation and customer communication. |
The Continuing Rise of Experiential Deliveries
As a consequence of the increased prominence of omni-channel retail strategies, we’re seeing changing perceptions of last mile logistics among senior leaders at larger retailers. Today, the last mile is considered by executives less as a set of operational challenges and more as a critical touchpoint opportunity in the overall holistic customer experience.
Delivery Experience Gap in Last Mile Logistics
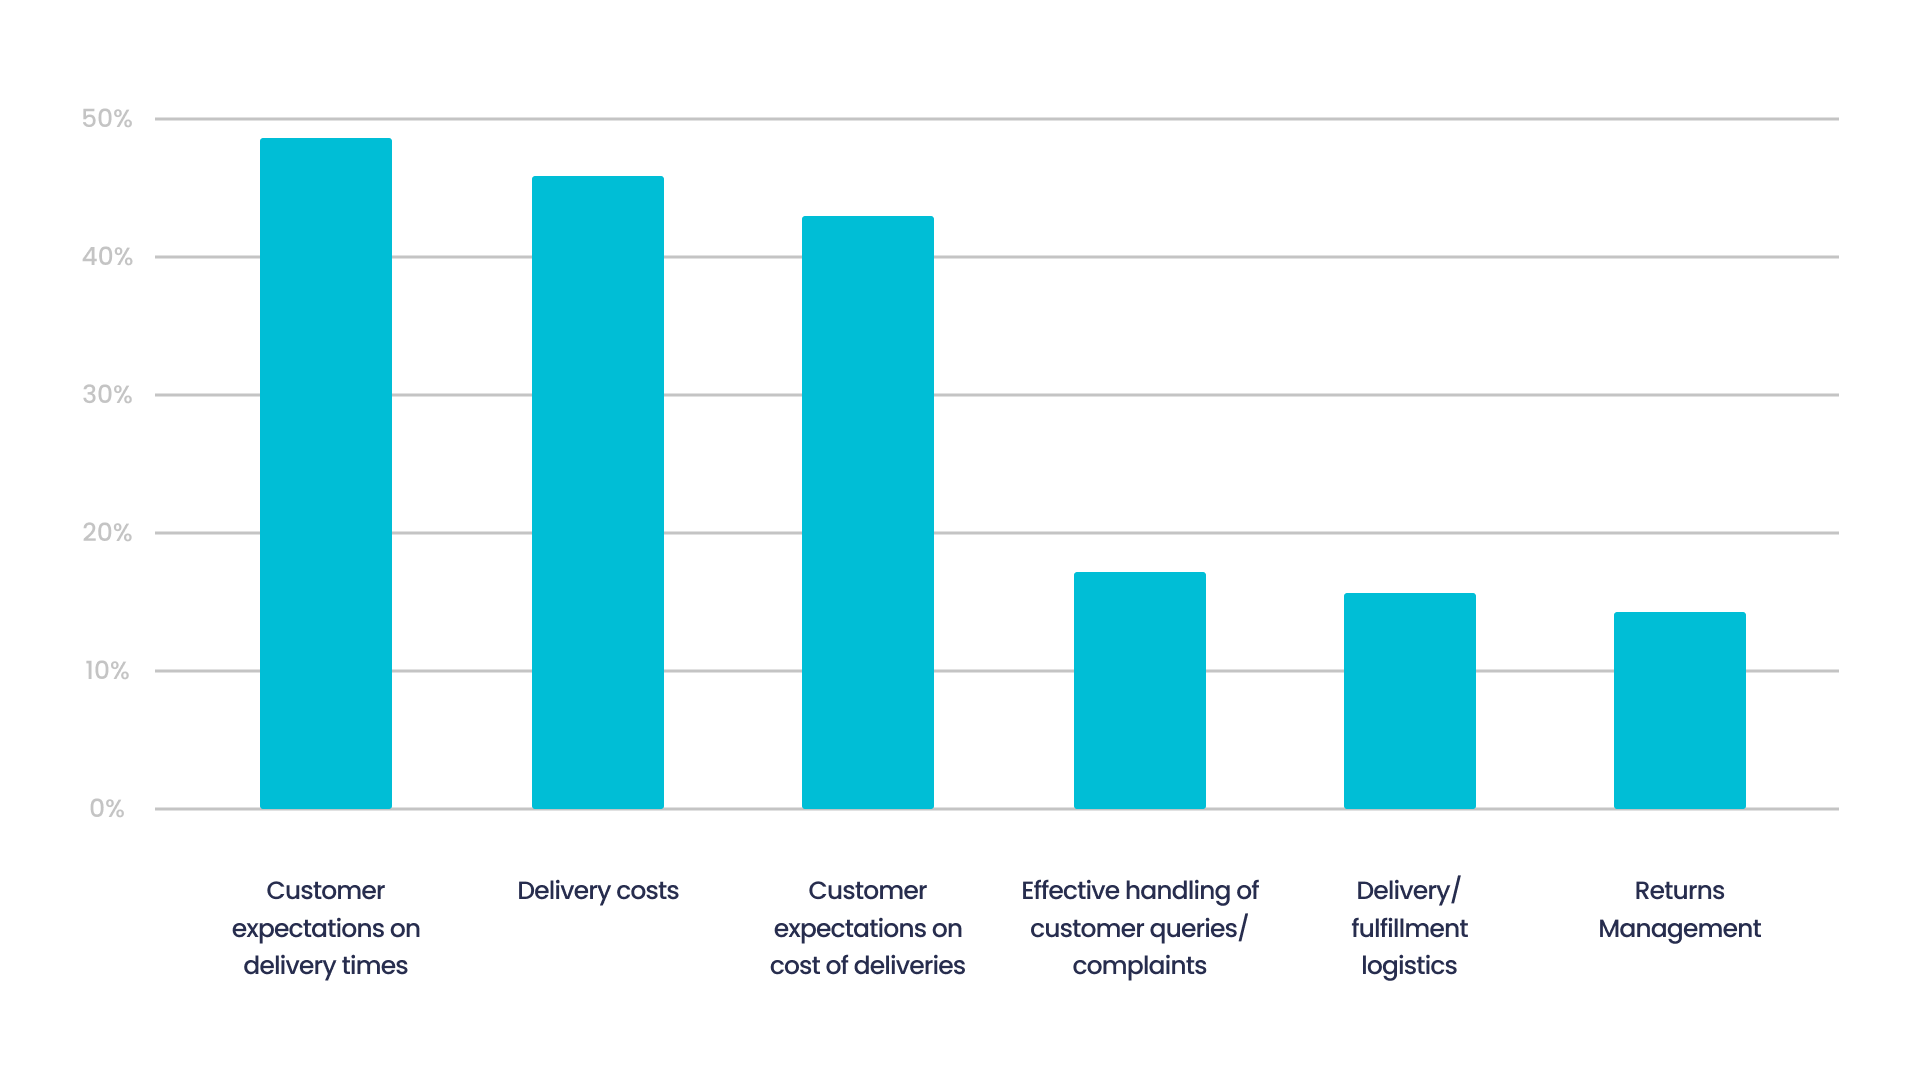
As such, it’s hardly surprising that three of the top four last mile concerns (Oracle) for retailers directly relate to customers, with expectations around delivery times (49%) and low-cost shipping (44%), as well as effective handling of customer queries and complaints (18%) identified as significant pain points. For most, there remains a very real delivery experience gap that prevents them from winning the last mile of ecommerce, with more than half of consumers having abandoned an online purchase at checkout (IMRG) for delivery-related reasons.
For most, there remains a very real delivery experience gap that prevents them from winning the last mile of ecommerce…
One in two shoppers now (Oracle) expects at least some degree of real-time visibility into the status of their deliveries. And this is something the industry has by and large recognised, with 60% of retailers listing online access to order tracking as the most impactful way of improving the delivery experience (IMRG).
(Source)
But with 41% of consumers giving up on a purchase because of the lack of convenient delivery options, it’s critical for retailers to understand that the delivery experience starts at checkout, well before a parcel has been loaded into a van.
Out of Home Deliveries
Out of home (OOH) delivery methods including lockers, PUDO (pick-up, drop-off) and other curbside or in-store pickup options are growing in popularity as retailers find new ways to accommodate customer expectations while also mitigating failed deliveries. According to Last Mile Experts, more than 40% of all PUDO points across the EU have been established since 2019, while OOH delivery routes are 3-4 times more efficient than delivering door to door.
It’s critical for retailers to understand that the delivery experience starts at checkout, well before a parcel has been loaded into a van
Smart Scheduling
The increasing prominence of interoperable supply chain management systems, for both retailers and their logistics partners, is creating data ecosystems that open up exciting new opportunities. One example of this is ‘smart scheduling’, by which ecommerce platforms can execute real-time queries of future scheduled delivery slot availability across multiple third-party carriers in order to surface more accurate information to consumers at checkout.
ConclusionA shift in perspective for retailers and their delivery partners to see the last mile as part of a holistic customer experience is leading to a greater emphasis on last mile tracking and flexible delivery options. Retailers must recognise that the delivery experience starts at checkout, before an order has even been placed. |
Emissions Continue Upwards Trajectory
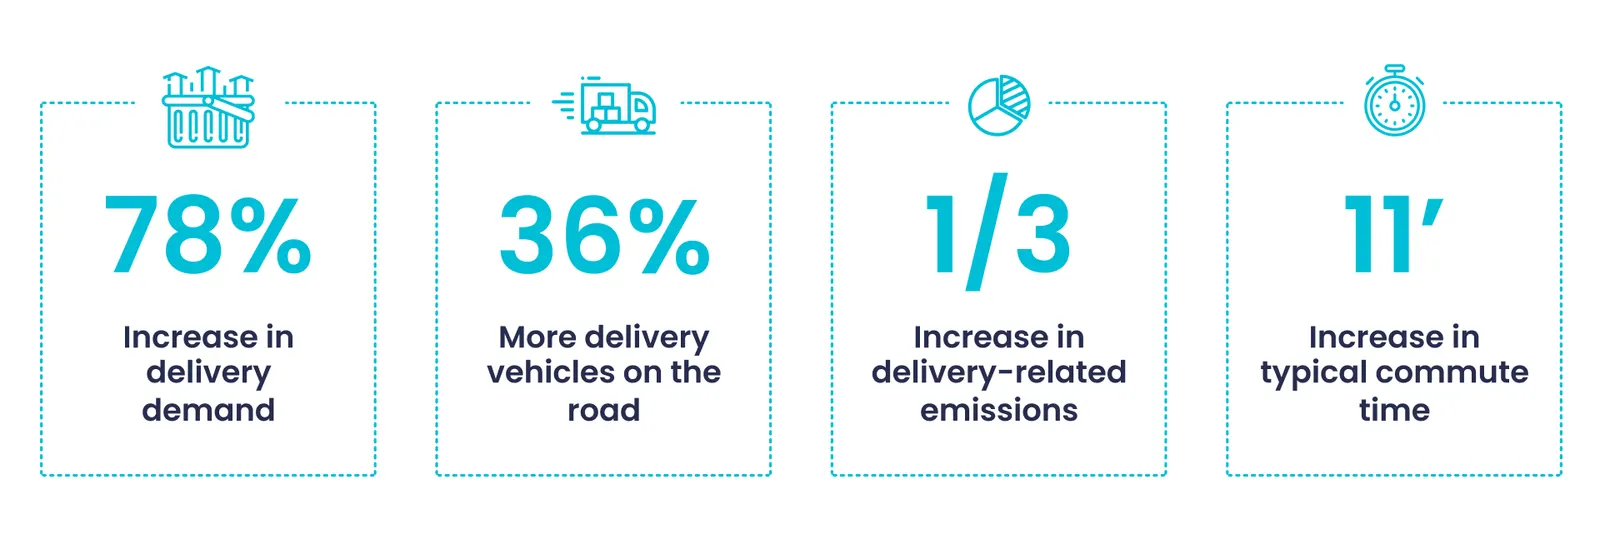
Revenues from ecommerce across Europe are expected to rise as much as 30% in 2021. The World Economic Forum anticipates that between now and 2030, demand for urban last mile delivery will nearly double, growing by 78%.
As a result of this demand, there will be 36% more delivery vehicles on the roads in the world’s largest 100 cities within the next decade, causing delivery related emissions to rise by over 30% and lengthening the typical commute time by 11 minutes.
(Source)
These are concerning figures given the greater scrutiny that is today being paid to sustainability and emissions in the last mile in particular.
Further Reading: Learn More About Sustainability in the Last Mile
Measurement of CO2 Emissions
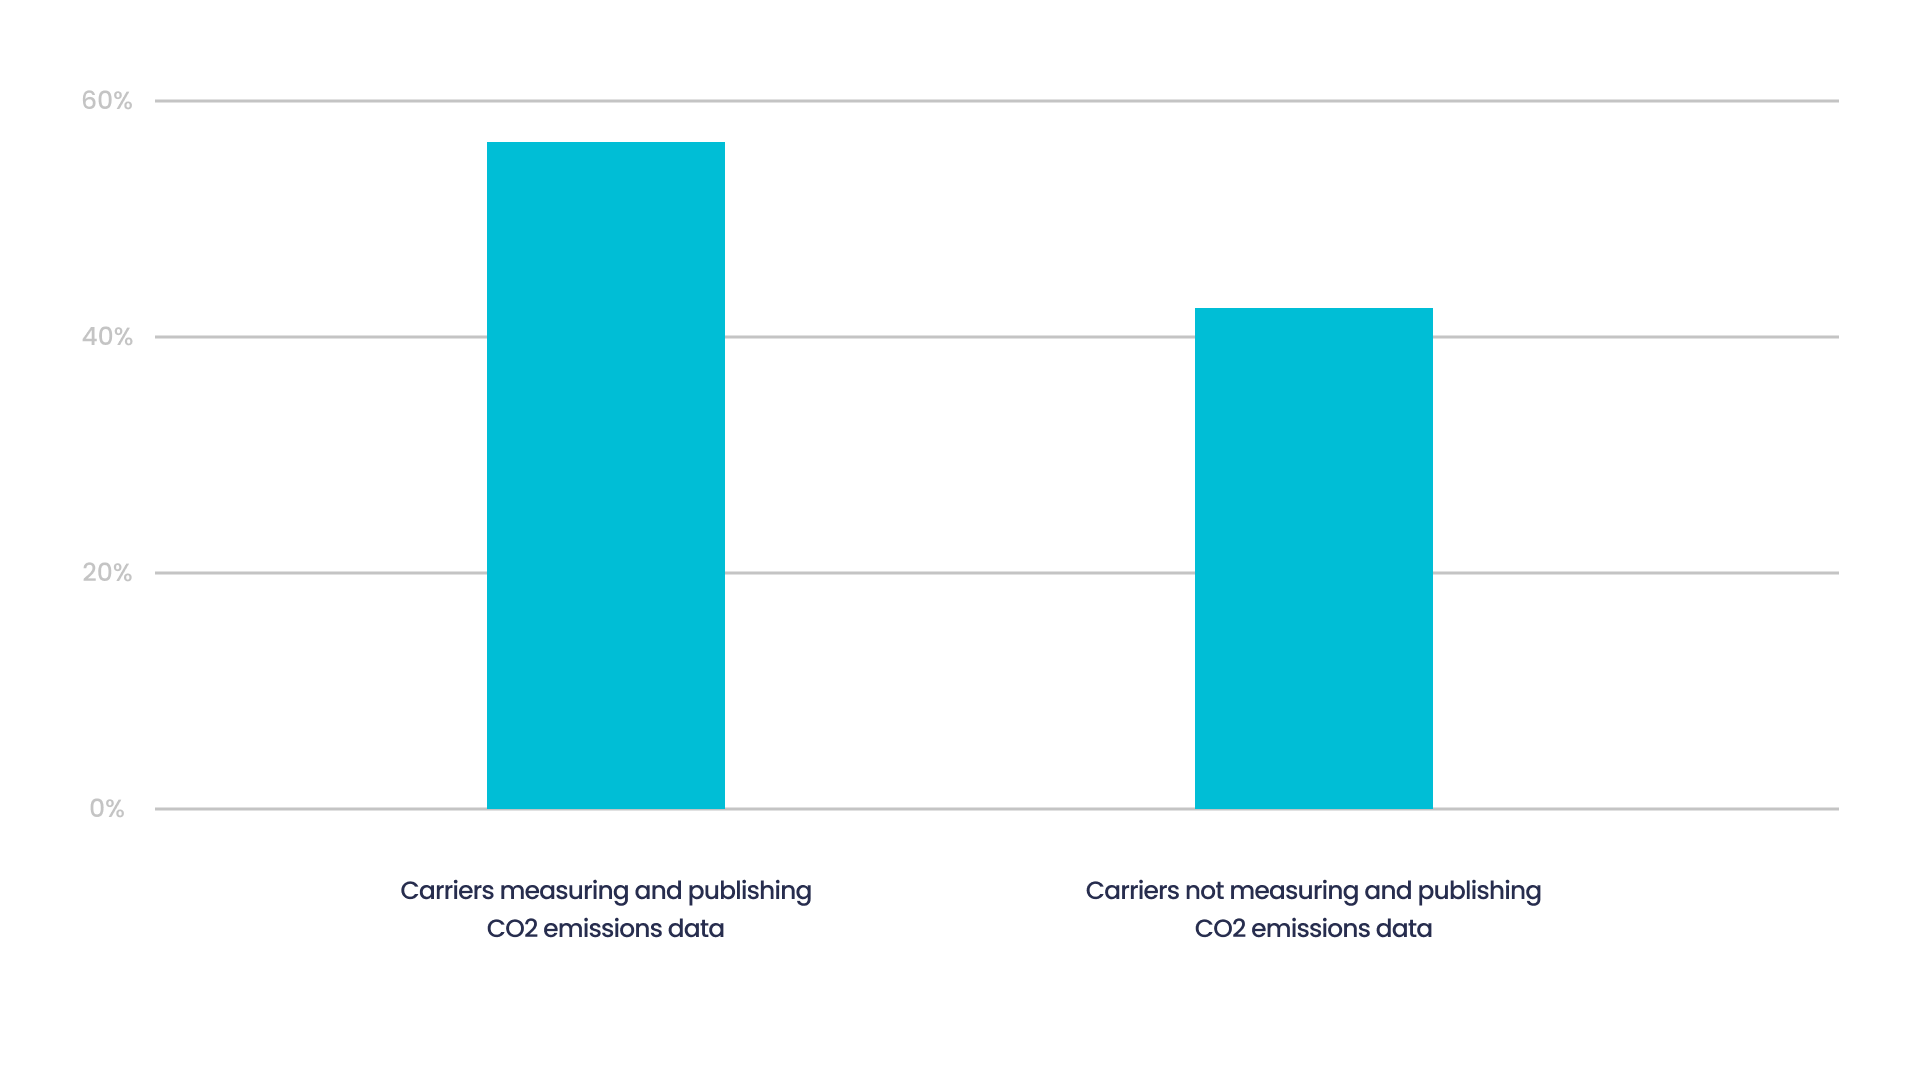
Aside from global multinational organisations such as DHL and IKEA that have already made pledges to go carbon neutral by 2050 and electrify their home delivery fleet respectively, research suggests that many enterprises still don’t actually track emissions data. In fact, a survey by the Foundation for Future Supply Chain looking at large logistics companies in particular revealed that only 57% currently measure and publish carbon emissions data.
(Source)
Space for Tech Innovations to Flourish
While these statistics may paint a bleak picture, it’s important to recognise that two of the biggest influencers of changing corporate behaviour, government legislation and consumer expectations, have been getting increasingly greener in recent years.
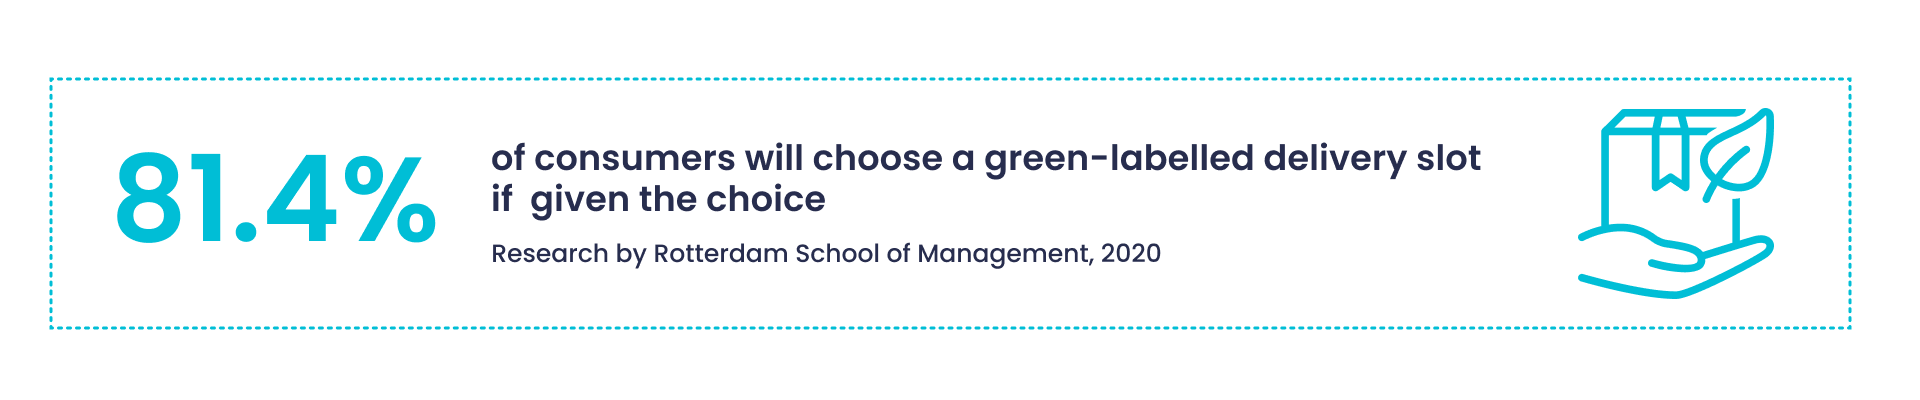
The EU and UK governments are making moves to ban new sales of petrol-burning vehicles within the next 10-15 years and invest in the required infrastructure to support mass adoption of electric vehicles. Similarly, consumer appetite is there for more sustainable delivery options, particularly in Europe. According to research by Rotterdam School of Management, more than 4 in 5 consumers would prefer a greener delivery slot if it was available to them at checkout.
(Source)
Similarly, data from the UK indicates nearly half of consumers would be open to the possibility of paying more for a greener delivery.
Slot Steering Technologies
One example of a technology that is being developed in response to these legislative and consumer pressures is so-called slot steering technologies such as Smart Scheduling. This is a subset of pre-optimisation technologies deployed in the last mile to expose more information about future delivery slot availability to shoppers at the point of sale, with a view to encouraging a certain action.
At the first level, this can be giving real-time information about carrier availability through integrations between ecommerce platforms, last mile delivery management software and third-party logistics partner systems. Instead of forecasting slot availability, the last mile platform can instead surface real-time information based on carrier capacity and existing orders.
Beyond this, there is potential to encourage consumers to opt for greener time slots, as an example, by ranking delivery windows based on the proximity of a purchaser’s address to an already-confirmed order in the vicinity. This is a great way for retailers to ensure maximum efficiency of delivery operations by incentivising timeslots that allow for the highest possible drop density.
ConclusionLast mile delivery emissions look set to continue rising and not enough is being done across the industry to measure and track emissions data, let alone reduce them. But legislative and consumer pressure can accelerate the greenification of delivery behavior, with new technologies such as slot steering and smart scheduling giving green-minded organisations a way to tap into changing customer sentiment for more sustainable deliveries. |
About Urbantz
The world’s biggest brands across retail, grocery, e-commerce and logistics use last mile experts Urbantz to manage their mission-critical last mile delivery operations.
Our platform is designed specifically for enterprises and our mission is to help them drive greater sustainability in their delivery operations, at any scale.
With Urbantz, you can:
Rapidly Scale Your Delivery Network
- Swiftly onboard new carriers and drivers in as little as minutes
- Deploy delivery services to new markets in a matter of days
- Manage complex carrier hierarchies from one screen
Cut Emissions in the Last Mile
- Drive higher first-time delivery success with Smart Scheduling
- Optimise towards greener delivery allocation and route planning
- Measure and track emissions across drivers and carriers
Delight Customers to Drive Loyalty
- Ensure on-brand delivery experiences between senders and recipients
- Configure tailored delivery workflows that follow any business logic
- Cut failed deliveries with driver-recipient communication channels
Make Data-Driven Business Decisions
- Get real-time visibility and control over your whole last mile network
- Create configurable dashboards and reports for informed decisions
- Deliver greater operational efficiency to cut your last mile costs